
GSTR-3B October 2026: The Last Return to Fix FY 2025-26 GST Errors (Complete Checklist)
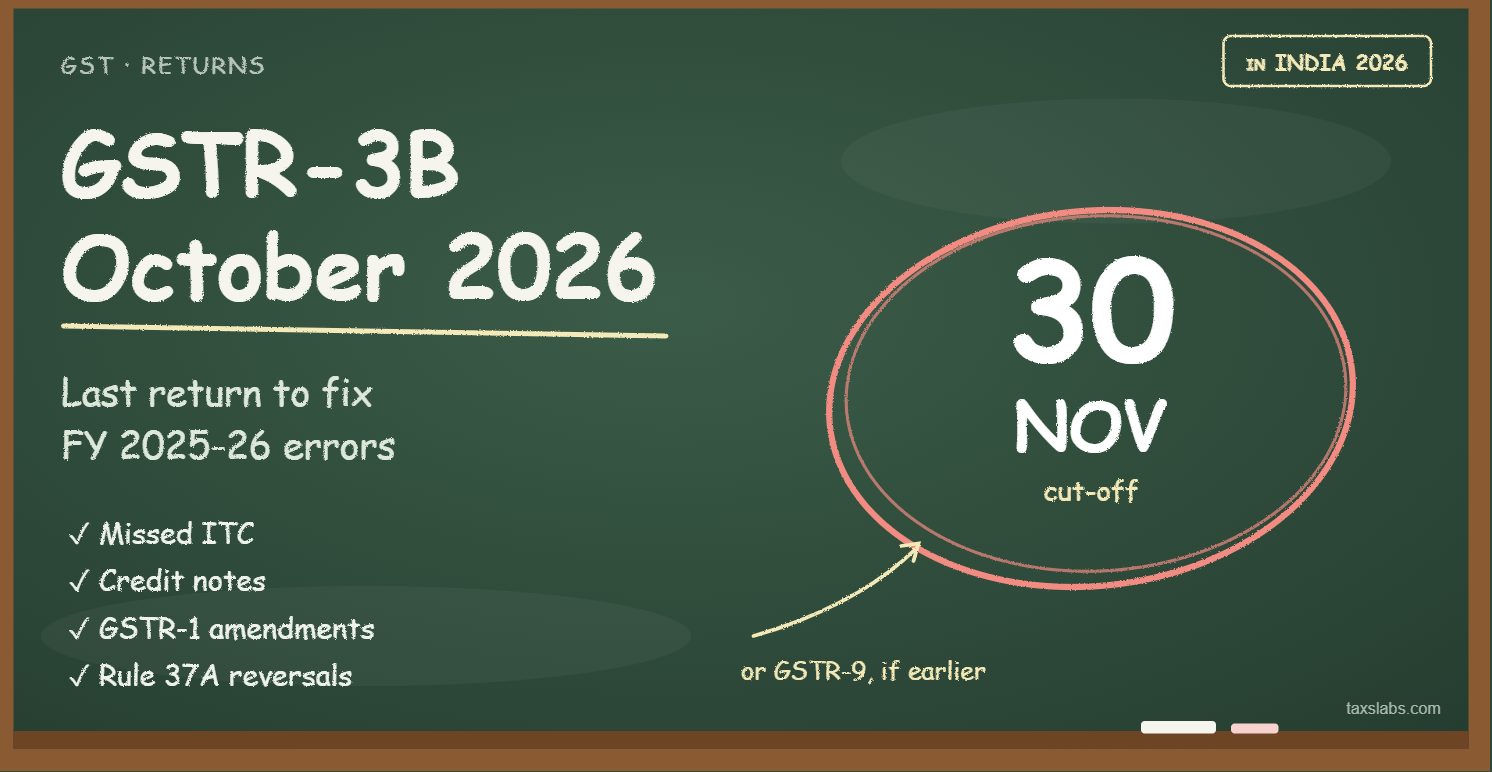
Every year, one GST return quietly becomes the most important filing of the season. This year it is GSTR-3B October 2026. Under the CGST Act, the window to claim missed input tax credit, declare credit notes and rectify returns for FY 2025-26 shuts on 30 November 2026. For monthly filers, the October return is the last one filed before that date.
So the GSTR-3B October 2026 is not a routine monthly return. It is your final chance to recover lost credit, correct wrong invoices and close FY 2025-26 cleanly before the annual return. In this guide, you will find the exact legal deadlines, the dates that matter for monthly and quarterly filers, a correction-by-correction checklist, worked ₹ examples, and what you can still do once the window closes.
Why GSTR-3B October 2026 Is the Last Correction Window for FY 2025-26
Four provisions of the CGST Act share the same cut-off. Each one ends on 30 November following the end of the financial year, or the date of furnishing the annual return, whichever is earlier. Since Finance Act 2022 moved these limits from the September return to 30 November, the October return has become the natural last stop for monthly filers.
| Provision | What it controls | Last date for FY 2025-26 |
|---|---|---|
| Section 16(4) | Availing ITC on invoices and debit notes of the year | 30 Nov 2026 or GSTR-9 filing, if earlier |
| Section 34(2) | Declaring credit notes to reduce output tax | 30 Nov 2026 or GSTR-9 filing, if earlier |
| Section 37(3) | Rectifying details furnished in GSTR-1 | 30 Nov 2026 or GSTR-9 filing, if earlier |
| Section 39(9) | Rectifying details furnished in GSTR-3B | 30 Nov 2026 or GSTR-9 filing, if earlier |
| Rule 37A | Reversing ITC where supplier did not file GSTR-3B by 30 Sep 2026 | In a GSTR-3B filed by 30 Nov 2026 |
You can read the exact proviso in the official text of Section 37 of the CGST Act on the CBIC portal. The same wording appears in Sections 16(4), 34(2) and 39(9).
Key due dates for the October 2026 returns
| Date | Day | Compliance | Who |
|---|---|---|---|
| 22 / 24 Oct 2026 | Thu / Sat | GSTR-3B for July to September 2026 quarter (State-wise) | QRMP filers |
| 31 Oct 2026 | Sat | Practical last date to issue FY 2025-26 credit notes | All suppliers |
| 11 Nov 2026 | Wed | GSTR-1 for October 2026 | Monthly filers |
| 13 Nov 2026 | Fri | IFF for October 2026 (optional, B2B records) | QRMP filers |
| Before GSTR-3B | — | GSTR-1A for October 2026 (one-time) | Monthly filers |
| 20 Nov 2026 | Fri | GSTR-3B for October 2026 | Monthly filers |
| 25 Nov 2026 | Wed | PMT-06 tax payment for October | QRMP filers |
| 30 Nov 2026 | Mon | Statutory cut-off for FY 2025-26 corrections | All taxpayers |
| 31 Dec 2026 | Thu | GSTR-9 (and GSTR-9C where applicable) for FY 2025-26 | Eligible taxpayers |
Always confirm due dates on the GST portal before filing, because extensions are notified from time to time.

Quarterly (QRMP) filers: your window closes on 22 or 24 October
This is the point most small businesses miss. If you file quarterly under QRMP, your GSTR-3B for October to December 2026 is due only in January 2027, well after the cut-off. Therefore, for you, the July to September 2026 GSTR-3B is the last return in which FY 2025-26 ITC can be claimed or rectified. It is due on 22 or 24 October 2026, depending on your State, which leaves only days from today.
In addition, B2B outward corrections can still go through the October IFF by 13 November, and GSTR-1A for the July to September quarter can be filed before the quarterly GSTR-3B. B2C corrections, however, do not fit in IFF, so they must be completed in the current quarterly cycle.
Do not file GSTR-9 early
The phrase “whichever is earlier” is a trap. If you furnish GSTR-9 for FY 2025-26 on, say, 5 November 2026, your window closes on 5 November, not 30 November. As a result, any ITC you later discover cannot be claimed. File the October GSTR-1 and GSTR-3B first, then the annual return, which is due by 31 December 2026.
Outward Supply Corrections in GSTR-1 and GSTR-1A
Errors on the sales side hurt twice. They distort your liability, and they block your customer’s ITC. Because GSTR-3B Table 3 is now auto-populated and locked to GSTR-1, GSTR-1A and IFF, all liability corrections must happen upstream. Our GSTR-3B hard-locking guide explains why editing GSTR-3B directly no longer works.
What to check in FY 2025-26 sales data
- Missed invoices that were billed in the books but never reported in GSTR-1.
- Wrong customer GSTIN, which sends the ITC to the wrong buyer.
- B2B invoices reported as B2C, a common reason buyers chase suppliers in October.
- Wrong place of supply, that is, IGST charged instead of CGST and SGST, or the reverse.
- Wrong rate or taxable value, including post-rationalisation rate errors from September 2025 onward.
- HSN summary mismatches between Table 12 and invoice-level data.
- Advances received for services where tax was not paid at the time of receipt.
For most of these, use the amendment tables (B2BA, B2CLA, B2CSA, CDNRA) in the October GSTR-1. Then, if something still needs fixing after GSTR-1 is filed, use GSTR-1A, which can be filed only once per tax period and before GSTR-3B. For the mechanics, see our GSTR-1A amendment guide.
Wrong place of supply: pay first, then claim refund
Where IGST was paid instead of CGST and SGST, or the other way round, you cannot simply transfer the amount. You pay tax under the correct head and claim a refund of the wrong head under Section 77 of the CGST Act and Section 19 of the IGST Act. Rule 89(1A) allows the refund application within two years from the date of paying tax under the correct head. Consequently, the October return remains the cleanest point to fix the reporting for FY 2025-26.
Credit Notes for FY 2025-26 Supplies: The Section 34(2) Cut-off
Credit notes are where the October deadline bites hardest. Under Section 34(2), a credit note for a supply must be declared in the return for the month in which it is issued, and not later than 30 November following the end of the financial year of the supply, or the annual return date, if earlier.
In practice, a credit note dated in November 2026 falls in the November return, which is filed in December. That is too late. Because the GSTR-3B October 2026 picks up its liability from that GSTR-1, every credit note against an FY 2025-26 supply should be dated on or before 31 October 2026 and reported in the October GSTR-1.
Debit notes and the buyer’s side
Debit notes are different. There is no outer time limit for issuing them, and since 1 January 2022 the ITC time limit for a debit note is linked to the financial year of the debit note itself, not the original invoice. On the buyer’s side, credit notes from suppliers arrive in IMS. Accepting them reduces your ITC, so make sure the reversal figure is correct, especially where you had not claimed full credit originally.
One more point: Finance Act 2026 amended Sections 15(3) and 34 on post-sale discounts. Check whether those changes have been notified before relying on them. In either case, the 30 November 2026 limit for FY 2025-26 credit notes still applies.
Claiming Missed ITC in GSTR-3B October 2026
For buyers, the GSTR-3B October 2026 is the last return in which leftover FY 2025-26 credit can be taken. We have covered the Section 16(4) rule in depth in our Section 16(4) ITC deadline guide. Here, the focus is on what to do in the October cycle.
Where missed credit usually hides
- Invoices that appeared in GSTR-2B but were never booked in the purchase register.
- Invoices booked but kept pending in IMS and then forgotten.
- Supplier invoices uploaded late; these appear in your October GSTR-2B only if the supplier reports them in the October GSTR-1 by 11 November.
- IGST on imports, which comes from ICEGATE data rather than supplier GSTR-1.
- RCM tax paid during the year where the corresponding ITC was not claimed.
- Credit reversed under Rule 37 that can now be re-availed after paying the vendor.
Find missing credit in minutes. Upload your purchase register and GSTR-2B to the free GST ITC reconciliation tool to spot unclaimed, mismatched and excess ITC before you file the GSTR-3B October 2026.

ITC Reversals You Must Finish by 30 November 2026
The October return is not only about claiming credit. It is also the last return to complete several mandatory reversals for FY 2025-26.
Rule 37A: supplier did not file GSTR-3B by 30 September
Rule 37A applies where your supplier reported an invoice in GSTR-1, so it reached your GSTR-2B, but did not file GSTR-3B for that period by 30 September 2026. You must reverse that ITC in a GSTR-3B filed on or before 30 November 2026, which for monthly filers means the GSTR-3B October 2026 at the latest, with interest if the credit was utilised. Once the supplier files the return, you can re-avail the credit in a later GSTR-3B.
Rule 37: vendors unpaid beyond 180 days
If you have not paid a supplier within 180 days of the invoice, Rule 37 requires reversal with interest in the return for the period right after the 180 days. When you pay, you can re-avail the credit, and the Section 16(4) time limit does not apply to that re-availment. Even so, October is the right moment to clean up all FY 2025-26 vendor ageing.
Rule 42 and Rule 43 annual true-up
Businesses with exempt and taxable supplies must compute the final common-credit reversal for the year before the due date of the September return. For FY 2025-26, that is the September 2026 GSTR-3B, due on 20 October 2026 for monthly filers. If you missed it, pay any short reversal through DRC-03 with interest rather than waiting.
Excess or blocked ITC claimed during the year
Review Section 17(5) items such as motor vehicles, food and beverages, club memberships and personal-use goods. If credit was wrongly claimed and utilised, interest runs at 18% per annum under Section 50(3).
Reverse Charge, Interest and Other Liabilities
Unpaid reverse charge liability is one of the most common audit findings. Before filing the October return, check FY 2025-26 payments for goods transport agency services, advocate fees, security services, sponsorship, import of services and renting of commercial property from unregistered persons.
Pay any missed RCM tax with interest in the GSTR-3B October 2026. For ITC on such tax, CBIC Circular 211/5/2024-GST clarified that where the supplier is unregistered, the relevant financial year for Section 16(4) is the year in which the recipient issues the self-invoice. Where the supplier is registered, it is the year of the supplier’s invoice. So, for registered-supplier RCM on FY 2025-26 invoices, October is the last chance to take the credit.
What Happens After 30 November 2026
Once the cut-off passes, FY 2025-26 becomes a one-way street. You can still pay more tax, but you cannot reduce liability or take new credit for that year.
- DRC-03 remains open. Short-paid tax can be paid voluntarily with Section 50 interest.
- GSTR-9 is disclosure, not correction. It reports ITC of FY 2025-26 claimed between April and November 2026 in the relevant tables, but it cannot be used to claim new credit.
- Re-availment survives in limited cases, such as Rule 37 credit after paying the vendor.
- The three-year bar is separate. Under Sections 37(5) and 39(11), GSTR-1 and GSTR-3B cannot be filed after three years from the due date. For example, an unfiled October 2023 GSTR-3B (due 20 November 2023) becomes time-barred after 20 November 2026.

Case Study: One Business, One Final Clean-up
Consider a Ludhiana polymer manufacturer filing monthly. In the third week of October 2026, its accountant runs the year-end GST clean-up for FY 2025-26:
| Finding | Amount | Action in October 2026 cycle |
|---|---|---|
| Eligible ITC not claimed | ₹1,84,000 | Claim in GSTR-3B Table 4A |
| Supplier not filed GSTR-3B by 30 Sep (Rule 37A) | ₹42,300 | Reverse in GSTR-3B Table 4B |
| Sales return on February 2026 sale | ₹18,000 GST | Credit note dated 29 Oct, reported in October GSTR-1 |
| Unpaid GTA RCM | ₹1,300 | Pay with interest; claim ITC |
| Wrong GSTIN on one B2B invoice | ₹72,000 GST | Amend through B2BA in October GSTR-1 |
The net effect is roughly ₹1,60,000 of cash saved (₹1,84,000 + ₹18,000 − ₹42,300, with the RCM credit offsetting the RCM payment), and a customer relationship protected. Above all, every item is completed in returns filed before 30 November 2026, and GSTR-9 is filed only in December.

Step-by-Step Filing Sequence for GSTR-3B October 2026
Follow this sequence so each correction lands in the right form, in the right order:
- Reconcile ITC for April 2025 to March 2026. Match the purchase register with GSTR-2B for all 12 months and list eligible credit not yet taken, with invoice numbers and tax amounts.
- Clear IMS pending records. Accept, reject or record reversal against every FY 2025-26 invoice and credit note still pending in the Invoice Management System.
- Issue pending credit notes by 31 October 2026. Sales returns, rate differences and excess billing on FY 2025-26 supplies must be dated in October so they reach the October GSTR-1.
- Fix outward supply errors in GSTR-1. Correct GSTIN, value, rate, place of supply and HSN errors through amendment tables in the October GSTR-1, filed by 11 November 2026.
- Use GSTR-1A for last-minute liability fixes. Because GSTR-3B Table 3 is locked to GSTR-1, file GSTR-1A once, after GSTR-1 and before GSTR-3B, for any remaining October corrections.
- Complete Rule 37 and Rule 37A reversals. Reverse credit for vendors unpaid beyond 180 days and for suppliers who did not file GSTR-3B by 30 September 2026, with interest where due.
- Discharge pending reverse charge liability. Pay RCM tax missed during FY 2025-26 with interest and claim the corresponding ITC where eligible.
- File GSTR-3B for October 2026 by 20 November. Claim the reconciled ITC in Table 4A, report reversals in Table 4B, and verify the liability before submission.
- File GSTR-9 only after October returns. Furnish the annual return for FY 2025-26 by 31 December 2026, after all corrections, because filing it earlier closes the window.
If you prepare outward data from Excel, the free GSTR-1 preparation tool helps you build clean October GSTR-1 data, including amendments and credit notes, before upload. Step-by-step portal help is also available on the official GST tutorial site.
Key Takeaways
- For monthly filers, GSTR-3B October 2026 (due 20 November) is the last return to fix FY 2025-26.
- Quarterly filers must finish FY 2025-26 ITC claims in the July to September return due 22 or 24 October 2026.
- Credit notes on FY 2025-26 supplies should be dated by 31 October 2026 to reach the October GSTR-1.
- Correct liability in GSTR-1 or GSTR-1A, because GSTR-3B Table 3 is locked.
- Complete Rule 37A, Rule 37 and blocked-credit reversals before the cut-off.
- Do not file GSTR-9 before your October corrections, since it closes the window early.
- After 30 November 2026, only DRC-03 payments and limited re-availments remain.
Frequently Asked Questions on GSTR-3B October 2026
Why is the October 2026 GSTR-3B the last chance to correct FY 2025-26 errors?
Sections 16(4), 34(2), 37(3) and 39(9) of the CGST Act close the window for claiming ITC, declaring credit notes and rectifying returns of a financial year on 30 November following that year, or on filing the annual return, whichever is earlier. For FY 2025-26 that date is 30 November 2026. The November 2026 return is filed in December, so for monthly filers the October 2026 return is the last one filed inside the window.
What is the due date of GSTR-3B for October 2026?
For monthly filers, GSTR-3B for October 2026 is due on 20 November 2026 and GSTR-1 on 11 November 2026. Quarterly (QRMP) filers file IFF for October by 13 November 2026 and pay tax through PMT-06 by 25 November 2026; their October to December GSTR-3B is due in January 2027.
I am a QRMP filer. Can I claim missed FY 2025-26 ITC in my October to December return?
No. That GSTR-3B is filed in January 2027, after the 30 November 2026 cut-off. For quarterly filers, the July to September 2026 GSTR-3B, due on 22 or 24 October 2026 depending on the State, is the last return in which missed FY 2025-26 ITC can be claimed.
Can I issue a credit note in November 2026 for a sale made in FY 2025-26?
You can issue it commercially, but it will not reduce your output tax. A credit note must be declared in the return for the month in which it is issued, and for FY 2025-26 supplies that declaration must happen by 30 November 2026. A November-dated credit note falls in the November return, filed in December, which is too late. Issue such credit notes on or before 31 October 2026.
Should I file GSTR-9 for FY 2025-26 before my October 2026 returns?
Generally no, if you still have corrections pending. The deadlines run till 30 November 2026 or the date you furnish the annual return, whichever is earlier, so filing GSTR-9 early closes the correction window early. File GSTR-1 and GSTR-3B for October first, then the annual return by 31 December 2026.
What is Rule 37A and why does it matter in October 2026?
Rule 37A requires a recipient to reverse ITC where the supplier reported the invoice in GSTR-1 but did not file GSTR-3B for that period by 30 September following the end of the financial year. For FY 2025-26 invoices, the reversal must be made in a GSTR-3B filed on or before 30 November 2026. The credit can be re-availed after the supplier files the return.
Can I pay additional GST for FY 2025-26 after 30 November 2026?
Yes. The deadlines restrict claiming ITC, reducing output tax and rectifying returns. Paying short-paid tax is always allowed through FORM GST DRC-03, along with interest under Section 50. What you cannot do after the cut-off is reduce liability or take new credit for FY 2025-26.
Where do I correct a wrong customer GSTIN on an FY 2025-26 invoice?
Use the amendment table (B2BA) in your October 2026 GSTR-1, or the October GSTR-1A before filing GSTR-3B. GSTR-1A cannot change the recipient GSTIN itself, so if you use GSTR-1A, the usual route is a credit note against the wrong GSTIN and a fresh invoice to the correct one. Complete it before 30 November 2026 so the buyer’s ITC is protected.
Conclusion
The GSTR-3B October 2026 is the last return in which you can claim leftover credit, reduce tax through credit notes and correct mistakes for FY 2025-26. Treat it as a year-end close, not a monthly routine. Reconcile all 12 months, clear IMS, issue credit notes by 31 October, fix GSTR-1 data, complete reversals and pay pending RCM. Then file GSTR-3B by 20 November and keep GSTR-9 for December.
Start this week, not in the last three days. Run your purchase data through the free GST ITC reconciliation tool, keep an eye on CBIC updates on the CBIC website, and use the complete GST guide on TaxSlabs for the rules behind each step.
